- Free Consultation: (202) 448-5136 Tap Here to Call Now


Repay Your Student Loans in Chapter 13 Bankruptcy


If you file Chapter 13 bankruptcy and choose not to repay your student loans, you could end up in a worse condition than before you filed. To be sure, you can defer repayment of your student loans during the entire duration of your bankruptcy case. But interest will continue to accrue on any unpaid balances, and you will wind up owing more when the case is over. That can seriously interfere with the core bankruptcy concept of a obtaining “fresh start.” To avoid this, you may want to repay your student loans in Chapter 13 bankruptcy.
Those sticky, sticky student loans
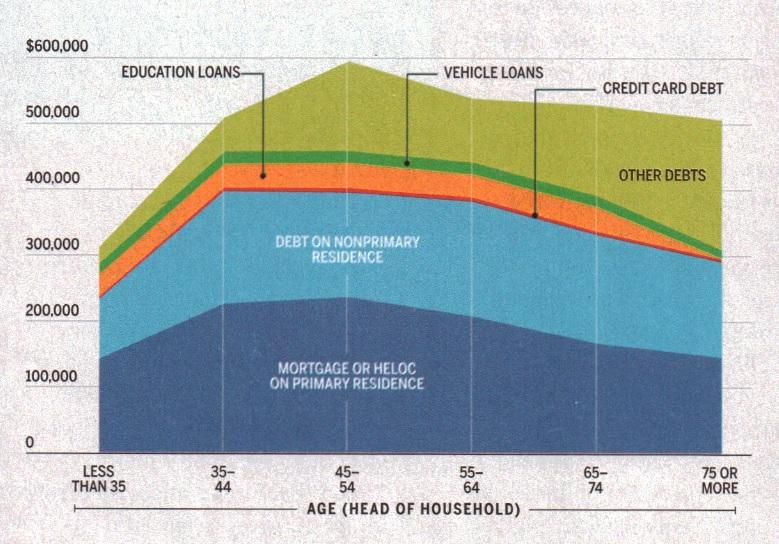
Just look at the graph below, which shows how “sticky” student loans are. The graph represents debt held by different age groups, and the orange bar represents student loans. On average, as you can see, student loans stay with us for much of our lives.
According to the National Association of Chapter 13 Trustees, between 1980 and 2010, the costs for college increased at a rate approximately five times the rate of inflation, and outstanding student loan debt now tops $1.5 trillion. Meanwhile, the default rates on student loans in the U.S. have nearly doubled since 2006. Many young people are filing Chapter 13 bankruptcy to escape the crushing burden of student loans.
Student loans are not dischargeable in Chapter 13
A Chapter 13 bankruptcy will not discharge your student loans. In many cases, you can repay only a percentage of your unsecured debts and discharge the rest of the balances. Unfortunately, however, you will still owe any unpaid student loan balances after you receive a Chapter 13 bankruptcy discharge. The Bankruptcy Code treats student loans differently than it does any other type of unsecured debt.
Call is growing for bringing back the discharge for student loans in bankruptcy. On June 21, 2018, the non-profit, non-partisan National Bankruptcy Conference (NBC) released a position paper recommending reinstatement of the discharge of student loans. The paper notes that many student loans are for ineffective educational programs or programs that the debtor never completes. Astonishingly, almost half of all students who enter college do not graduate and receive a degree.
The editorial board at Bloomberg recently put it best: Let Student Borrowers Declare Bankruptcy, Already.
Repay your student loans in Chapter 13 bankruptcy
While student loans may not be discharged, you can repay your student loans in Chapter 13 bankruptcy. In bankruptcy, the “classification” of claims means grouping together creditors for similar repayment through the Chapter 13 Plan. Most courts have held that student loans are inherently different from other unsecured creditors due to their nondischargeability and are thus are subject to separate classification.
The usual purpose of separately classifying student loan debts is to pay the student loan creditor more than what is being paid to other unsecured creditors. Classifying student loans separately can be accomplished through 11 U.S.C. 523(a)(8), 1122 and 1322 of the Bankruptcy Code.
[I]t is often in the debtor’s interest to pay off
as much of the student loan debt
in the Chapter 13 plan as is permissible.
One way to pay more on the student loan
than on other unsecured debts
is to provide in the Plan that the debtor
will maintain direct ongoing monthly payments
to a student loan creditor . . .
National Bankruptcy Conference,
Student Loan Dischargeability (2018)
You may be able to reduce your payout to unsecured creditors by maintaining your monthly payments to student loans. At the confirmation stage, courts look to balance the financial needs of bankruptcy debtors with those of their creditors. For example, a Chapter 13 Plan may not provide for 100 percent repayment of student loans while the remaining unsecured creditors receive 0 percent. Such a Plan would not be fair to the non-student-loan unsecured creditors.
Talk to a bankruptcy attorney
Claim classification and Plan calculation are as much an art as a science. The bankruptcy trustee, United States Trustee, and bankruptcy judge will closely examine your income and expenses, calculation of disposable income, and claims register to determine whether your Chapter 13 Plan should be confirmed. If you want to repay your student loans in Chapter 13 bankruptcy, talk it over with an experienced bankruptcy attorney.
They Called. They're Glad They Did.
Couldn’t have chosen a better attorney! He was extremely down-to-earth, explained everything clearly, and always made himself available whenever I had questions—even after my case was over. He helped me through a difficult financial situation and also helped put me in a better...

Thank you so much, for being an awesome lawyer. You took care of me and my husband when all the lawyer offices that we called did not answer or even seems to care, you stepped in and save the day. You listened to us and you took care of us as if we were family. You listened and...

Choosing Lee Legal to help me file for bankruptcy was the best decision I have made in a long time. Brian explained the entire process and answered every single question I posed. The mountain of building stress due to my situation lifted the second Brian walked me through the...

Brian Lee from Lee Legal was an amazing attorney to work with. He took his time, reviewed my documents and we discussed my situation thoroughly. He explained the process and my options as well as gave his recommendation. Not only did he assist, but he ensured that I knew this...

Brian is hands down the most amazing bankruptcy lawyer out there. he answered all my questions and even supported issues that arose 2 years after discharge Thank you for everything!!!!!!

Mr. Brian Lee made a stressful financial situation much easier to handle. Having a guide who is both deeply knowledgeable and approachable makes a massive difference when you are navigating financial challenges for the first time. THE BEST!!!

Search no more! Brian is trustworthy, friendly, attentive, and knowledgeable. Bankruptcy is never an easy decision to make however when it's time you'll need a good lawyer by your side. This is the man to do the job. I had zero hiccups throughout the entire process. Please do...

I was very nervous and scared about going through this process. But Brian was very knowledgeable and helped me through it. I was notified about any and all updates to my case and he was very responsive when I had questions regarding any concerns I had. Although a bit nerve...

I wanted to share my sincere appreciation for Brian and the support he provided during a very difficult time for my grandmother. We were not wealthy, but Brian treated us with genuine kindness and respect, making sure we felt comfortable throughout the entire process. He took the...

This is your last stop in your searches for an attorney. After numerous research and interview with many lawyers, I decided to hire attorney Brian Lee. He is extremely knowledgeable, personable, attentive and diligent. He went above and beyond to file my ch 7 bankruptcy and get a...

Brian provided me with a very detailed analysis about my potential case after our first consultation. He promptly responded to all my complex questions, especially navigating student loans and some tax discussions. He is very professional and experienced at what he does, I would...
